TTD’s spend story has shifted sharply since March, with its share of DSP revenue falling from 18.9% to 10.8% by August and combined CPMs dropping 43% as other demand partners moved in the opposite direction. But beneath that decline, OpenPath tells a different story: while overall TTD spend continued to shrink, OpenPath remained relatively stable, holding around 26% to 30% of TTD spend for most of the period and showing greater CPM stability than SSP-routed demand. With the post-June decline continuing despite TIDs being passed, the bigger question becomes what is really driving the shift in TTD’s spend and what OpenPath’s resilience reveals about where that demand is moving.

Report Overview
This edition of the DataBeat Programmatic Trends Report draws on anonymized data from partners across the DataBeat network to surface U.S. programmatic advertising performance and trends for September 2026. The report benchmarks August 2026 results against both July 2026 and August 2025, delivering a dual lens of month-over-month and year-over-year perspective.

Key Highlights
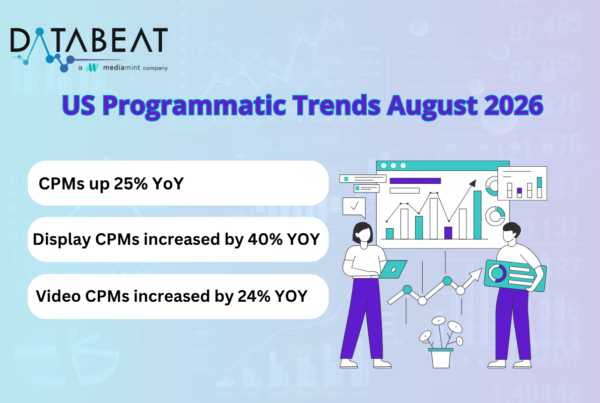
- On a month-over-month basis, Display CPMs rose 14.9% and Video CPMs declined 3.4%, producing a 19.3% overall CPM gain.
- Year-over-year, Display CPMs climbed 12.9% while Video CPMs surged 14.3%, lifting overall CPM 43.0%.
- August’s rebound reflects the back-to-school and early Q3 demand ramp reversing the mid-summer softness. With budgets returning, publishers should hold floor-price discipline, lean into direct deals, and keep header-bidding competition high to capture the demand recovery as it builds into the Q4 peak.
Want to know more? Please download the full report for a detailed breakdown.